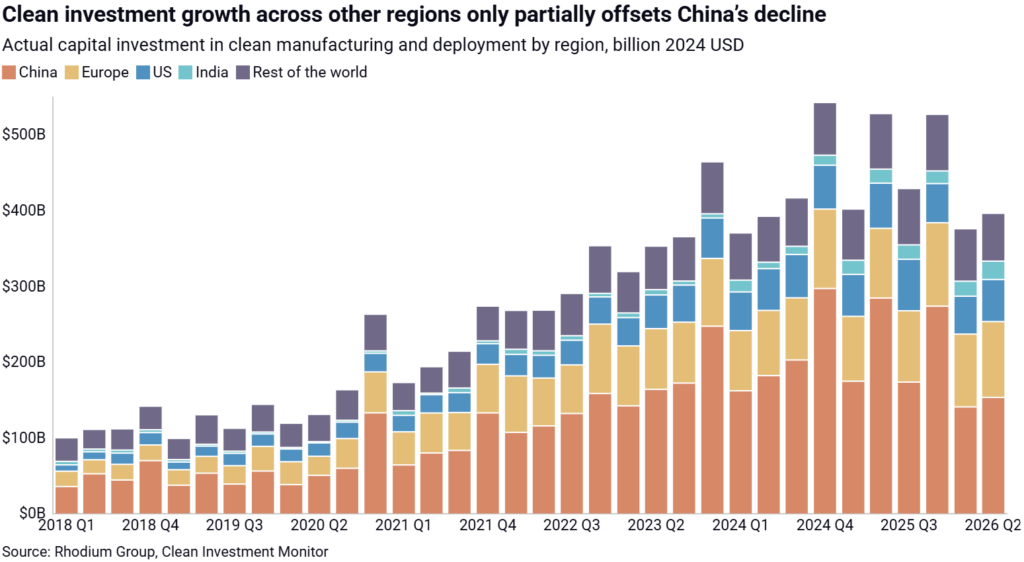

Global clean technology investment weakened in the early months of 2026 after a record year in 2025. The headline figure, reported by research firm Rhodium Group, found that total investment was 17% below the same period in 2025.
The variance between Q1 and Q2 in 2026 was considerable, even at the scale of billions of dollars.
The report notes, “Investment fell sharply in Q1 of 2026, declining by $151.1 billion, or 28%, from the elevated levels recorded at the end of 2025 and back to levels comparable to Q1 2024. Investment rose 5% in Q2 to $395.4 billion, partially offsetting that decline, but was still 25% below Q4 2025.”
The comparative fall in overall investment was related to China, the largest investor in cleantech, which had been building at rapid pace and frontloading its investments. A shift to market-based pricing and other policy reforms and transitions were noted. This means, for the first time, China’s share of global cleantech manufacturing and industry investment dipped below one-third.

In terms of other locations, Q2 was highlighted for positives in increasing investment, with rises of 23% in India, 11% in the United States, 4% in Europe from Q1, plus 9% by China from the falls in Q1 2026. Investment in India and Europe also exceeded Q2 2025 levels.
Electric power investment: Batteries
In terms of electric power investment, Rhodium notes the rise of solar deployment as a result of the closure of the Strait of Hormuz is more a limited regional dynamic than a global trend, though it may still play out given petroleum and diesel prices remain elevated.

In terms of utility-scale storage, it logged falling investments, falling 14% from H2 2025 and 16% from H1 2025.
The report noted, when accounting for stationary and mobility batteries, “Battery manufacturing investment was down about 13% in Q1 2026 relative to Q4 2025 before falling modestly in the second quarter of 2026, putting investment 26% below Q2 2025 levels.”
Despite actual investment drops, global battery manufacturing announcements held steady at roughly $23 billion in both Q1 and Q2 2026, matching Q4 2025 levels. Consequently, batteries accounted for 50% of all announced manufacturing and industry investment in the first half of the year.
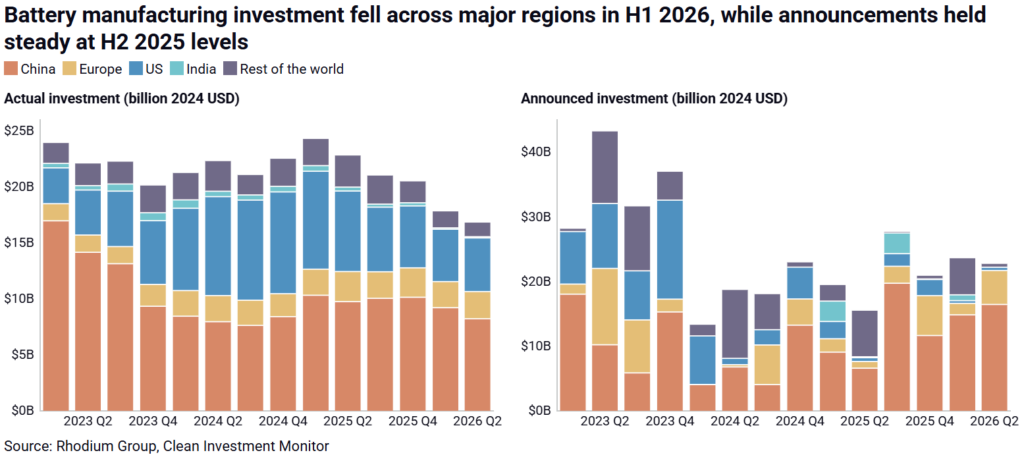
As has been seen with companies switching manufacturing lines towards stationary storage, falling investment in new mobile battery manufacturing capacity was offset by expanding activity in the stationary storage sector.
Europe also saw meaningful new announcements in battery manufacturing in H1 2026, although they were down 20% from the second half of 2025. Elsewhere, major new upstream battery material facilities were planned in Spain and France.
In the rest of the world, new announcements were up by more than 700% in H1 2026 compared to modest H2 2025 levels, with major announcements from Indonesia, Japan, South Korea, and Vietnam.
The report noted that US battery announcements hit a record low in the first half of 2026 at $915 million, the lowest levels since the passage of the Inflation Reduction Act in 2022.
Announcements in China were shifting from mobile to stationary battery applications, with 41% of announced investment coming from dedicated stationary storage or mixed-application facilities in the first half of 2026.
Solar
Solar investment was the largest segment, at 62% of global electric power investment in H1 2026. In the US, Europe, India, and other parts of the world, investment in new intermittent renewables stayed stable or grew in H1 2026 relative to H1 2025.
US solar announcements dominated Q2 2026, accounting for $8.0 billion of the $10.4 billion global total, driven almost entirely by two $2.9 billion projects in Texas and New Mexico.
Regional distribution of solar manufacturing investment shifted strongly, with India’s share rising from 5% to 48% over the same period, as domestic tariffs and requirements affect the industry. In India, announced upstream capacity jumped significantly from Q4 2025 to Q2 2026: wafers rose from 5 GW to 24 GW, and polysilicon went from zero to 10 GW.

Still, investment in new solar fell in H1 2026 relative to H1 2025, down 33%, primarily due to China.
The post Global cleantech investment fell in H1 2026; momentum holds outside of China appeared first on Energy Storage.